Advantages of Different Types of Income to Qualify for a Mortgage in Ontario
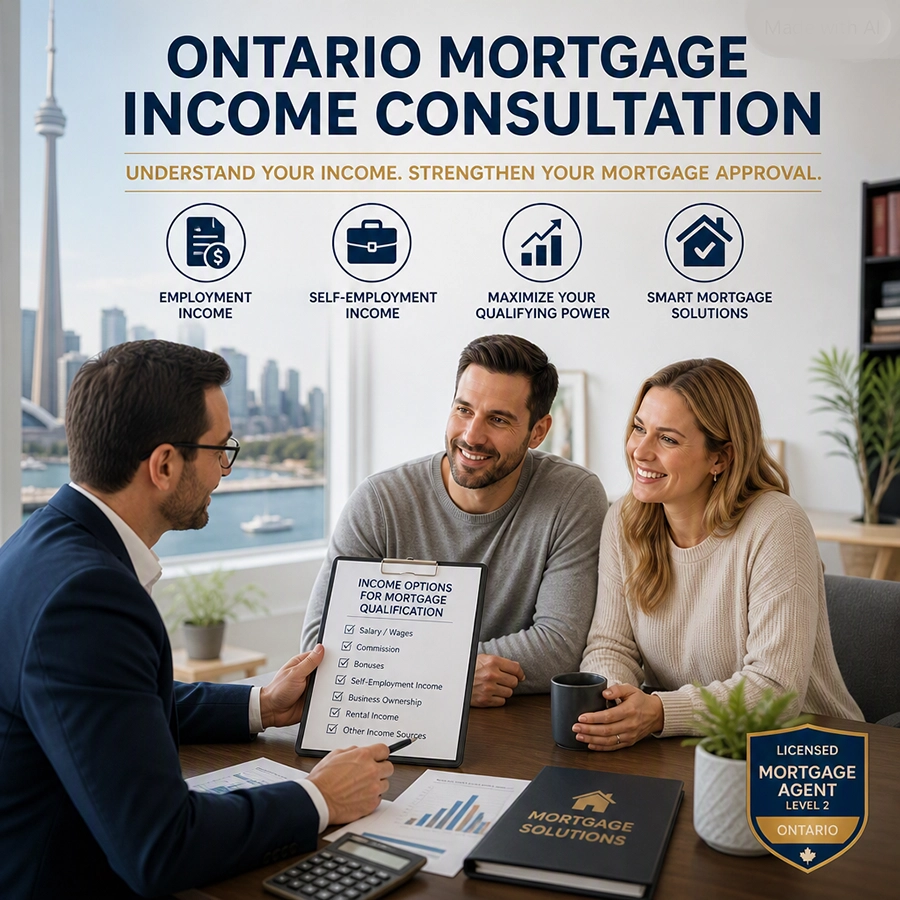
Qualifying for a mortgage in Ontario depends heavily on how your income is structured. While lenders follow strict federal guidelines, both employment income and self‑employment income can be used effectively — each offering its own advantages when presented properly through a Licensed Mortgage Agent Level 2.
Below is a clear breakdown of the two most common income types in Ontario and how each can strengthen a mortgage application.
1. Employment Income (T4 Income)
Employment income is the most straightforward income type for lenders to assess. It offers several advantages:
✔ Stable and predictable earnings
Lenders prefer consistent pay-cheques because they reduce risk and make qualification easier.
✔ Easier documentation
With most lenders, borrowers only need:
- recent pay stubs
- a letter of employment
- two years of T4s
- Notice of Assessment (NOA)
✔ Higher qualification power
Because employment income is predictable, lenders often allow higher debt‑service ratios, helping borrowers qualify for larger mortgage amounts.
✔ Ideal for first‑time buyers
Employment income provides the simplest path to approval, especially when paired with good credit and stable job history.
2. Self‑Employment Income (Business or Contract Income)
Self‑employed borrowers make up a growing portion of Ontario’s mortgage market. When structured correctly, self‑employment income offers strong advantages:
✔ Multiple income streams
Business owners often have several revenue sources, which can strengthen qualification when properly documented.
✔ Add‑backs increase usable income
Mortgage agents can highlight legitimate add‑backs such as:
- capital cost allowance
- business use‑of‑home expenses
- vehicle expenses
- non‑cash deductions
These increase the income lenders can use for qualification.
✔ Alternative lender flexibility
Self‑employed borrowers can qualify through lenders who:
- accept bank statements
- use gross business revenue
- allow stated‑income programs
- consider long‑term business stability
This opens the door to approvals even when traditional lenders decline.
✔ Ideal for entrepreneurs and contractors
Self‑employment income can be leveraged strategically to qualify for a mortgage that aligns with business growth and long‑term financial planning.
Which Income Type Is Better?
Both income types can qualify successfully — the key is how the income is presented. A Licensed Mortgage Agent Level 2 ensures your income is structured, documented, and optimized to meet lender guidelines.
📲 Ready to explore your mortgage options?
Start your secure online application and receive personalized guidance based on your income type and financial goals.