Recommended Ways to Save the Down Payment for a Home Purchase in Ontario
The Bank of Canada’s current prime rate is 4.70%. Saving for a down payment remains one of the biggest challenges for Ontario homebuyers. With housing prices continuing to rise, strategic planning and disciplined saving channels can make the difference between waiting and owning.
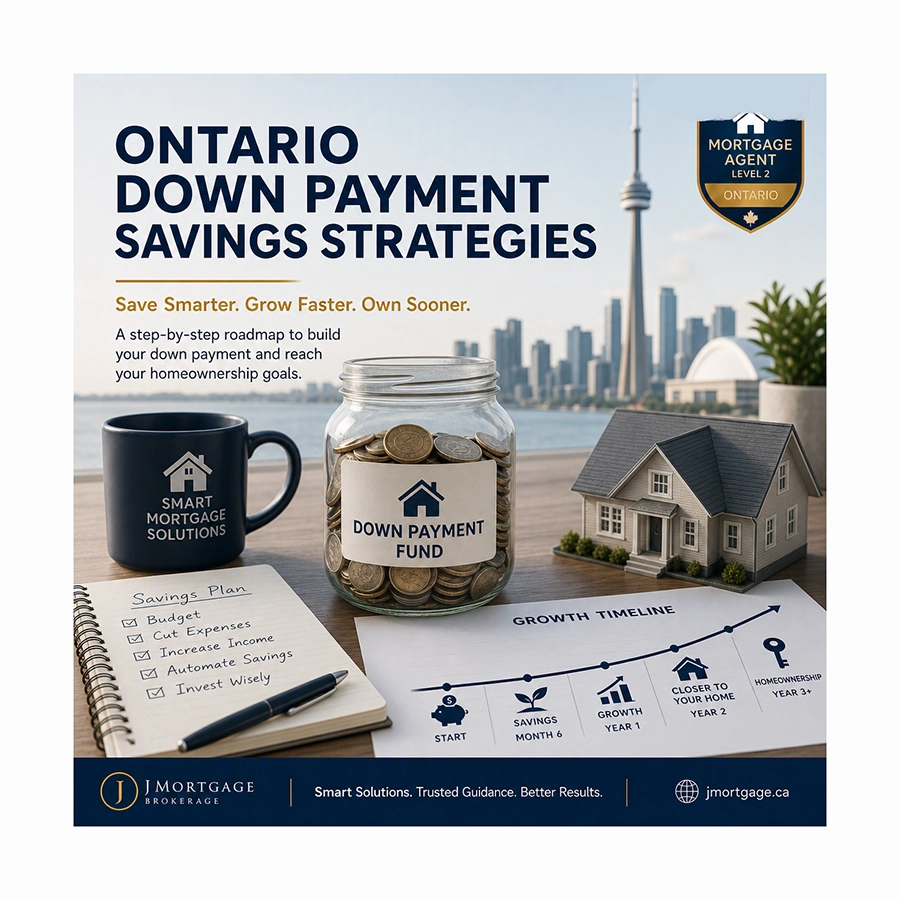
Below are the most effective, compliant, and practical ways to build your down payment — and the timing strategies that help you reach your goal faster.
1. Dedicated Savings Account
Open a separate high‑interest savings account exclusively for your down payment. This creates psychological separation from everyday spending and allows compound interest to work in your favor. Timing tip: Automate weekly transfers right after payday to build consistency.
2. Tax‑Advantaged Accounts (FHSA & RRSP)
Ontario residents can use the First Home Savings Account (FHSA) and RRSP Home Buyers’ Plan (HBP) to save tax‑free.
- FHSA: Contribute up to $8,000 per year (lifetime $40,000).
- RRSP HBP: Withdraw up to $35,000 tax‑free for your first home. Timing tip: Maximize contributions early in the year to benefit from tax deductions and growth.
3. Budget Reallocation
Review monthly expenses and redirect discretionary spending toward your down payment fund. Small adjustments — dining out less, renegotiating subscriptions, or refinancing high‑interest debt — can accelerate savings. Timing tip: Reassess your budget quarterly to capture new opportunities.
4. Gifted Funds or Co‑Saving
Family gifts are permitted under FSRA guidelines when properly documented. Alternatively, co‑saving with a partner or family member can double progress while maintaining transparency. Timing tip: Plan documentation early to avoid closing delays.
5. Short‑Term Investment Vehicles
For buyers with a 1‑ to 3‑year horizon, low‑risk GICs or money‑market funds can offer modest returns while preserving liquidity. Timing tip: Align maturity dates with your projected purchase window.
Would you like to find out more information for your mortgage? Visit www.jmortgage.ca